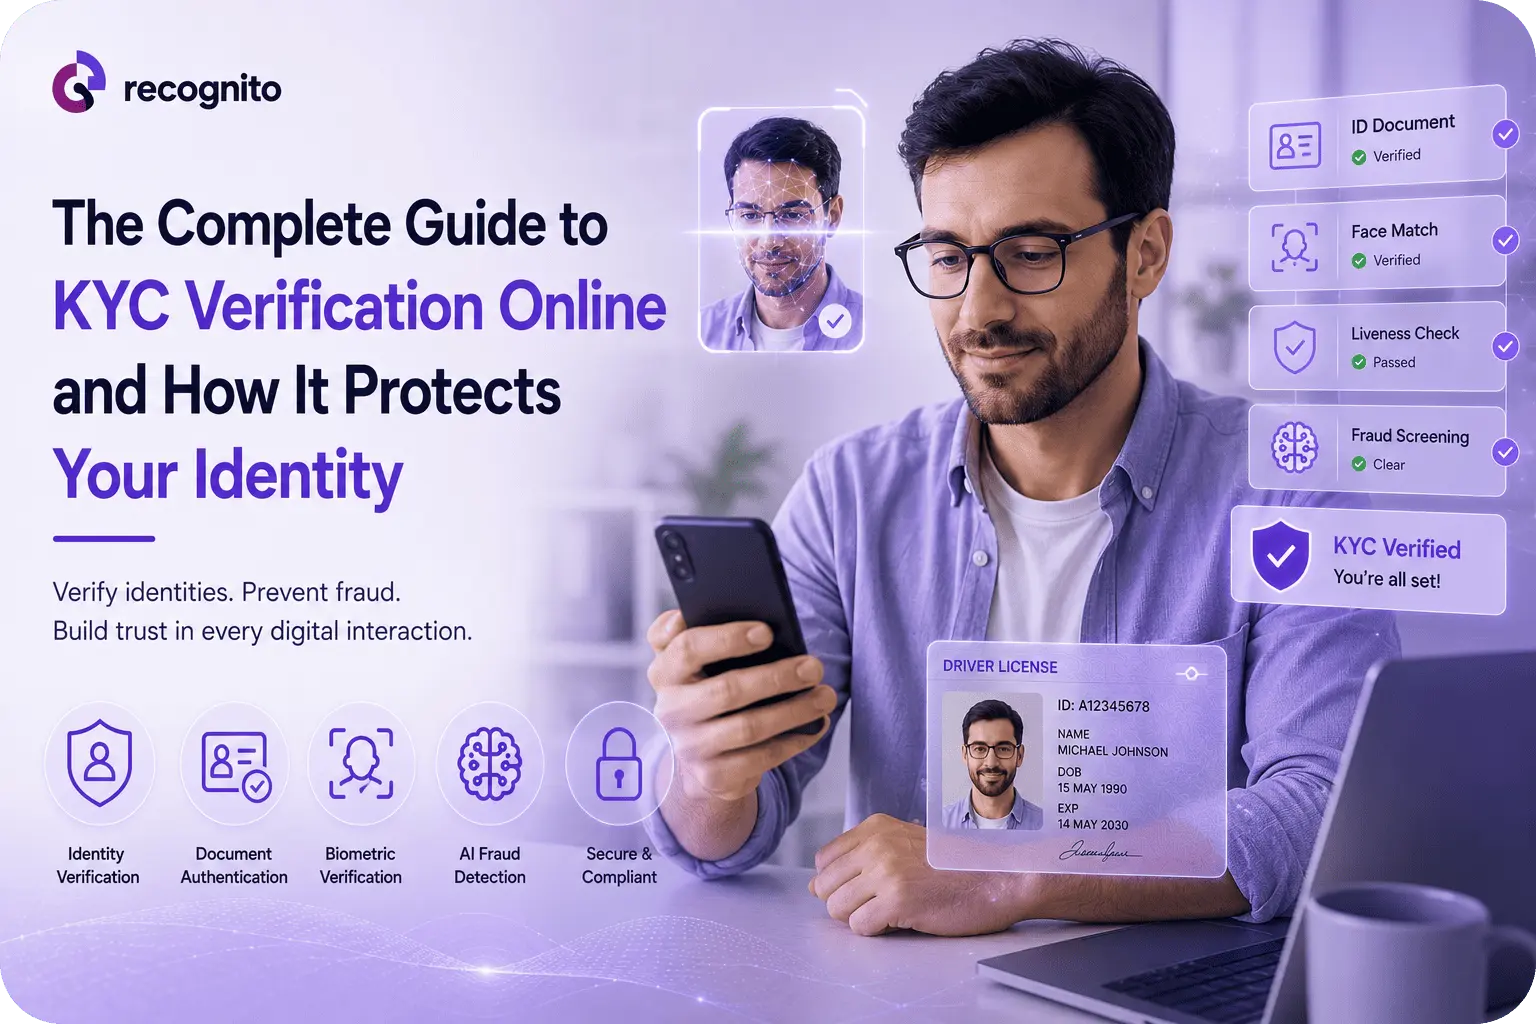
Opening a bank account, applying for credit, or joining a fintech platform can now happen entirely online. That convenience creates a difficult security challenge: the business must establish that the applicant is real, that the identity belongs to them, and that the submitted evidence is trustworthy.
KYC verification online brings those requirements into a digital workflow. Modern systems can combine identity-document recognition, document authenticity checks, facial verification, liveness detection, trusted-data validation, and risk-based review.
The goal is not simply to collect a customer’s ID. It is to gather enough reliable evidence to make a sound onboarding decision without creating unnecessary friction for legitimate users.
Why Online KYC Is More Than an ID Upload
A passport scan or photograph of an identity card is useful evidence, but it does not answer every KYC question.
An attacker may submit a stolen document, alter an image, use a counterfeit credential, or present a digital copy that looks legitimate. A genuine document can also belong to someone other than the person applying.
A strong online process therefore needs to establish several things:
- Does the document appear genuine?
- Is the document actually being presented by the applicant?
- Does the applicant match its portrait?
- Is the applicant physically present?
- Are the identity details consistent with trusted information?
- Does the application present unusual risk?
NIST’s current Digital Identity Guidelines distinguish identity proofing from authentication and emphasize resolving, validating, and verifying identity evidence. NIST SP 800-63-4 Digital Identity Guidelines
That makes KYC verification best understood as a layered evidence process rather than a single check.
How KYC Verification Online Works
Although implementations vary, a mature workflow often follows this sequence.
1. Capture identity evidence
The customer photographs an identity document with a phone or webcam. Good capture guidance helps the user position the document correctly and detects poor-quality images before deeper processing.
2. Recognize and extract document data
Computer vision and OCR identify the document type and extract fields such as name, date of birth, document number, and expiry date. Those details can then be compared with the application.
A document recognition solution can help businesses understand how this layer fits into the wider identity workflow.
3. Check authenticity and manipulation
Document analysis can examine structure, visual characteristics, machine-readable information, and other available indicators for inconsistencies.
FIDO’s Document Authenticity certification program addresses threats including counterfeit documents, physical and digital tampering, invalid documents, presentation attacks, and face morphing.
4. Match the customer to the document
A selfie or video can be compared with the portrait on the document. This creates a biometric connection between the applicant and the identity evidence.
5. Verify liveness
A face match alone does not prove that the applicant is physically present. Liveness adds a separate control against photographs, replayed video, masks, and other presentation attacks.
The role of liveness in protecting identity workflows is discussed in document liveness detection and identity fraud prevention.
6. Apply risk-based decisioning
Document results, biometric results, identity attributes, device information, and fraud indicators can be combined into a final decision.
A straightforward case may pass automatically. Conflicting evidence can trigger another verification step or manual review.
FATF’s Guidance on Digital Identity explains how reliable digital identity systems can support customer due diligence while regulated entities apply a risk-based approach.
How Online KYC Protects Customers
KYC is a business and regulatory process, but it also protects individuals whose identities could otherwise be misused.
Identity theft and impersonation
Stolen names, addresses, identification numbers, and other personal details can be used to open accounts or access services. Combining document evidence with facial verification makes simple impersonation harder.
Counterfeit and altered documents
Digital onboarding increases the importance of checking whether submitted identity evidence has been manipulated. A convincing image should not automatically be treated as a genuine credential.
For a deeper look at this problem, see document fraud detection techniques.
Synthetic identities
Fraudsters can combine legitimate and fabricated information to create identities that do not correspond cleanly to one real person. Multi-layer verification makes it harder to rely on a single stolen data point.
Account abuse after onboarding
Identity assurance can also support later controls such as account recovery, step-up verification, and fraud investigations.
Why Layered Verification Is Stronger
No KYC control is perfect.
OCR may correctly read a fraudulent document. A genuine document may be stolen. A facial match may be attacked with a presentation technique. A liveness check may fail because of poor lighting rather than malicious activity.
The solution is to give different controls different jobs.
| Verification layer | Main question | Typical risk addressed |
| Document recognition | What evidence and data are being presented? | Incorrect or incomplete data |
| Document authenticity | Does the document appear genuine? | Counterfeit or tampered IDs |
| Face matching | Does the applicant match the portrait? | Impersonation |
| Face liveness | Is the applicant physically present? | Presentation attacks |
| Risk analysis | Does the application look suspicious overall? | Coordinated fraud |
| Human review | Is additional judgment required? | Ambiguous cases |
Layering also improves failure handling. A poor document capture can trigger a retry, while a suspected counterfeit can be escalated without treating every failure as fraud.
Security Depends on More Than AI Accuracy
Vendor accuracy percentages rarely describe the whole production experience.
Performance can change with camera quality, lighting, document condition, device type, population, thresholds, network reliability, and workflow design. NIST’s identity proofing requirements emphasize fraud controls and multiple proofing methods and evidence types so assurance can be matched to risk.
A serious evaluation should therefore test:
- real customer devices and environments
- difficult capture conditions
- relevant counterfeit and tampering scenarios
- presentation and injection attacks
- false rejection and false acceptance
- retry and fallback behavior
- latency and service availability
The goal is to understand the complete onboarding system rather than an isolated model.
Choosing the Right KYC Technology
The right solution depends on the business model.
A fintech onboarding consumers remotely may prioritize camera-based document capture, facial verification, and liveness. A bank with large compliance teams may place more emphasis on orchestration and analyst review. A global business may require broad document coverage and multilingual support.
Integration matters too. Development teams need reliable APIs, predictable responses, mobile compatibility, useful failure states, and a clear way to pass verification outcomes into the decision engine.
When facial biometrics are part of that architecture, a biometric verification SDK can be evaluated alongside the rest of the stack.
For technical implementation work, the Recognito GitHub repository can provide an additional developer-oriented reference.
Privacy Is Part of KYC Security
Identity verification creates another responsibility: protecting the evidence collected.
A business should know what personal and biometric information is captured, where it is processed, what is stored, how long it is retained, and who can access it.
Data minimization matters because unnecessary identity data increases the consequences of a breach. Encryption, access controls, secure transmission, retention limits, and auditability should therefore be considered alongside verification performance.
The European Banking Authority’s remote customer onboarding guidelines tell financial institutions to use safe, effective, risk-sensitive onboarding practices and to assess the adequacy and reliability of remote onboarding tools.
What Businesses Should Measure
Approval rate alone is not enough to judge online KYC.
Useful metrics include:
Completion rate: How many legitimate customers finish verification?
Time to decision: How quickly does an applicant receive an outcome?
Manual-review rate: How much work remains after automation?
False rejection rate: How often are legitimate customers unnecessarily blocked?
Fraud detection performance: How effectively does the process identify suspicious applications?
Retry rate: How often must customers repeat a capture?
These measures reveal trade-offs that a single accuracy figure cannot. Tightening controls may reduce fraud but increase abandonment and manual reviews. Relaxing them may improve conversion while increasing fraud exposure.
KYC Verification Is Not the Same as KYC Compliance
Identity verification is a technical capability. KYC is the broader compliance and operating process.
A KYC program can include customer identification, identity verification, customer due diligence, risk assessment, recordkeeping, and ongoing monitoring. Installing an identity-verification API does not automatically make that program compliant.
Requirements also differ by jurisdiction and use case. Technology should support documented compliance procedures rather than substitute for them.
NIST’s SP 800-63A-4 identity-proofing guidance is focused on digital identity proofing rather than serving as a universal KYC regulation, but its evidence-based approach is useful when designing remote identity workflows.
Designing a Better Online KYC Experience
Security and customer experience should be designed together.
A confusing process can cause legitimate customers to abandon onboarding. Excessive retries increase support costs. On the other hand, a workflow optimized only for speed can allow weak identity evidence through.
Useful design choices include clear capture instructions, real-time quality feedback, fast processing, understandable error messages, secure retries, and risk-based escalation.
Most importantly, not every failed verification should be treated as fraud. A failed capture may result from glare, motion blur, a poor camera, or an unsupported document rather than a malicious attempt.
Where Online KYC Fits Into the Fraud Lifecycle
KYC is often the first major identity checkpoint, but it should not be the last.
After an account is approved, criminals may attempt account takeover, credential abuse, mule activity, or other forms of financial crime. A reliable onboarding record gives later security systems a stronger identity reference. Re-verification can then be used when risk changes, such as during sensitive account recovery or unusual activity.
This also means KYC systems should generate useful, auditable outcomes rather than a simple pass/fail flag. Fraud and compliance teams may need to know which checks succeeded, which failed, whether the customer retried, and why an application was escalated.
That information helps organizations investigate incidents and tune controls without unnecessarily repeating the entire onboarding process for every customer.
The Future of Online KYC
Online KYC is moving toward orchestration rather than isolated checks.
Document recognition, document authenticity, facial verification, liveness, fraud signals, and risk scoring can increasingly work as connected evidence sources. A low-risk application may require little intervention, while conflicting evidence can trigger stronger controls.
NIST’s fourth revision of its Digital Identity Guidelines expanded its treatment of fraud, injection attacks, forged media, and evaluation metrics. NIST SP 800-63-4 overview
That direction matters because attackers also adapt. A durable KYC architecture must be able to add new checks, tune thresholds, monitor outcomes, and change workflows without rebuilding the entire system.
The end goal is not to create the most complicated onboarding flow. It is to create a decision system that can gather trustworthy evidence with the least unnecessary friction.
Conclusion
KYC verification online gives businesses a practical way to establish identity remotely while reducing dependence on manual checks.
Its strength comes from combining controls rather than trusting one signal: document recognition, authenticity analysis, facial verification, liveness, risk assessment, and human review where necessary.
For businesses, the goal is not to automate every decision. It is to gather trustworthy evidence quickly, protect that evidence throughout its lifecycle, and apply the right level of scrutiny to each application.
For organizations building this infrastructure, Recognito provides biometric and identity-verification technologies that can support layered digital onboarding workflows.
Frequently Asked Questions
Is online KYC secure?
It can be, when document checks, biometric verification, liveness, fraud controls, secure data handling, and risk-based decisioning work together. No single control guarantees protection.
Does KYC verification prevent identity theft?
It can make impersonation harder by requiring stronger evidence than basic personal information, but it does not eliminate every fraud scenario.
Is a selfie enough for KYC?
Usually not. A selfie can provide biometric evidence, but robust verification generally connects the person to trusted identity evidence and uses additional controls such as liveness.
What happens when online KYC fails?
A failure should not automatically mean fraud. Good systems distinguish poor capture quality, mismatched information, suspected fraud, and inconclusive results, then use retries, additional verification, or human review.
What should businesses look for in an online KYC provider?
Evaluate document coverage, authenticity detection, biometric matching, liveness, fraud resistance, integration, privacy, performance, monitoring, and failure-handling processes.